25% off on product page · save $2.00
A Family Budget That Makes Room for Real Life
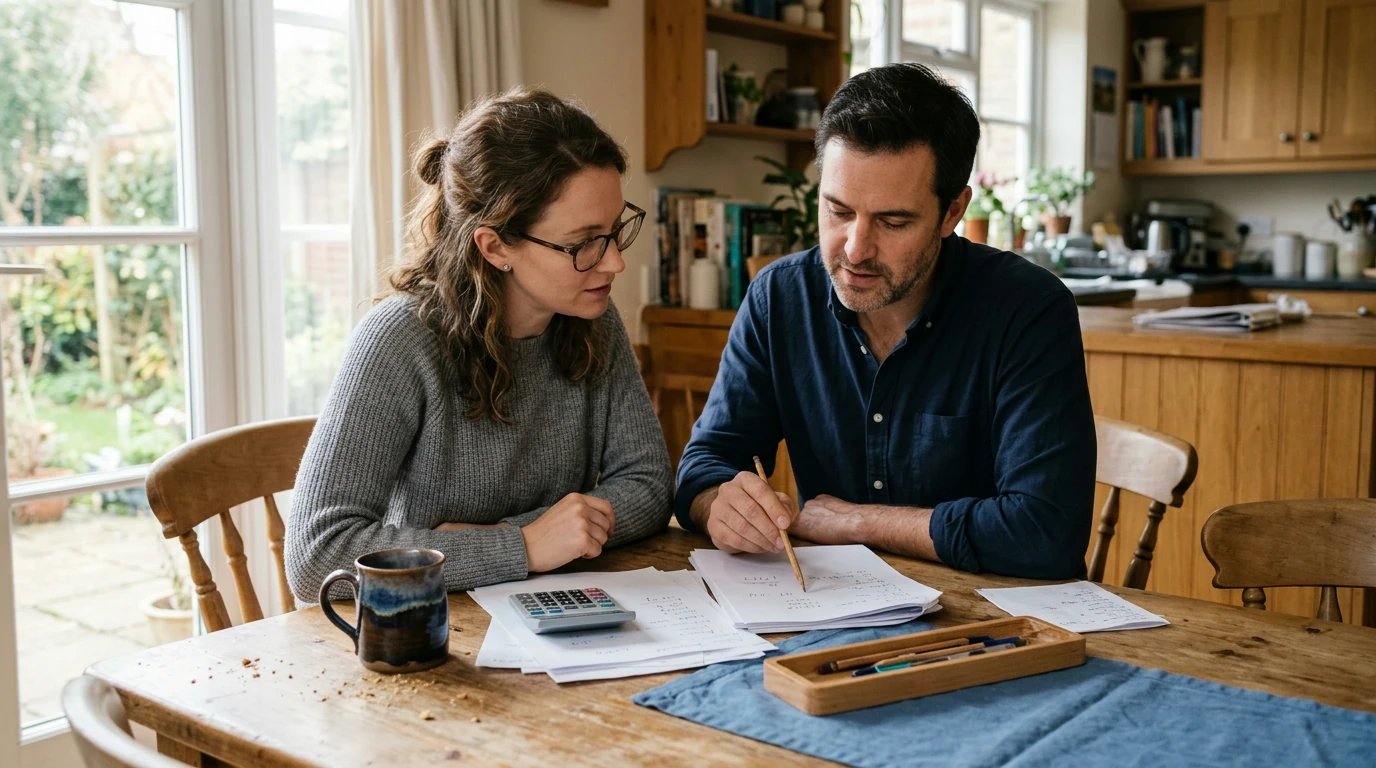
Write down each source of reliable monthly income, using take-home amounts after taxes and payroll deductions. Include regular paychecks and other income you can reasonably expect. If someone’s earnings vary, start with a conservative figure rather than the amount from their best month. That gives the household a plan it can use even when work is slower.
Choose one monthly view, whether paychecks arrive weekly, every two weeks, or once a month. You can still mark payday dates on a calendar to help time bill payments. Keep bonuses, gifts, and other irregular income out of the main plan until the money arrives. Then discuss whether it should cover a future expense, strengthen savings, or support another priority.
Record housing, utilities, groceries, transportation, insurance, childcare, and minimum debt payments. Check recent statements for subscriptions, school costs, and bills that appear only occasionally.
Give irregular expenses a monthly line of their own. Then subtract all planned spending from reliable income. A negative balance calls for changes before the month starts; a positive balance deserves a purpose, whether that is a future bill, savings, or a buffer.
Featured in this guide
Family Finance Freedom: Your Go-To Budgeting Checklist for Happy Wallets & Happier Homes | Digital Download | How to Budget Family Income Guide
Set aside what you can for emergencies and known future expenses. Then choose realistic amounts for flexible spending, such as takeout, activities, and hobbies. A plan is easier to use when it accounts for ordinary family life.
If spending exceeds income, review flexible categories first. Larger recurring costs may also be worth examining, though some cannot change quickly.
Choose a notebook, spreadsheet, or digital checklist that the people managing the money can understand. For a ready-to-use option, consider the Family Finance Freedom digital budgeting checklist. Review its product page to see whether its contents suit your household.
Meet briefly each week to compare actual spending with the plan. Focus on what changed and what to do next, not on blame. At month’s end, carry useful adjustments into the next budget.
Include minimum debt payments with essential expenses. If money remains after necessities and planned costs, decide together whether some should go toward balances. A monthly budget shows what may be available; it does not settle every repayment decision.
For a separate resource on that question, see the guide to paying off credit card balances. Review its product page before buying.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
It is also worth checking measurements, material notes, included parts, and compatibility details so the item matches the way it will be used after delivery.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
There is no single best choice for every family. Compare free options for shared access, spending categories, privacy, and ease of use; a spreadsheet or paper budget may be enough if everyone can keep it updated.
Family finance is how a household earns, spends, saves, and borrows money, along with the shared decisions behind those activities. It includes everyday bills as well as longer-term goals.
“Freedom finance” can mean different things depending on the business or resource using the name. The Family Finance Freedom download mentioned here is presented as a budgeting checklist for organizing a family-income plan; check its product page for its specific contents.
Leave a comment